NRI Banking Support UK: Streamlined NRE & NRO Account Assistance for British-Indians
Managing cross-border finances shouldn’t feel like navigating a maze of endless bureaucratic paperwork. Whether saving your UK earnings in tax-free fixed deposits or collecting property rentals back home, our dedicated NRI Banking Support UK service provides clear, reassuring, step-by-step guidance.
- Author Name: DiuMitra Cross-Border Advisory Team
- Reviewed By / Subject Matter Expert Name: Reviewed by Senior NRI Compliance & Banking Specialist
- Last Updated Date: Updated for 2026 Regulations (FEMA & HMRC DTAA Guidelines)
⚠️ Disclaimer: DiuMitra is an independent administrative support service and is not affiliated with the RBI, HMRC, or any commercial bank. We assist with document pre-screening and application compilation only. We do not offer financial, legal, or tax advice, and all final account decisions rest entirely with the respective banks and authorities.
UK-Based Administrative Help
Flawless Document Verification
Trusted by British-Indian Families
Transparent Fixed Pricing
Simplifying Cross-Border Banking for the British-Indian Community
For Non-Resident Indians (NRIs) and Persons of Indian Origin (PIOs) residing across the UK, maintaining fluid financial roots in India is both deeply personal and highly practical. Whether it is sending money to elderly parents, managing investments in Indian mutual funds, purchasing real estate in ancestral towns, or handling complex inheritances, having a functional banking setup is absolutely vital.
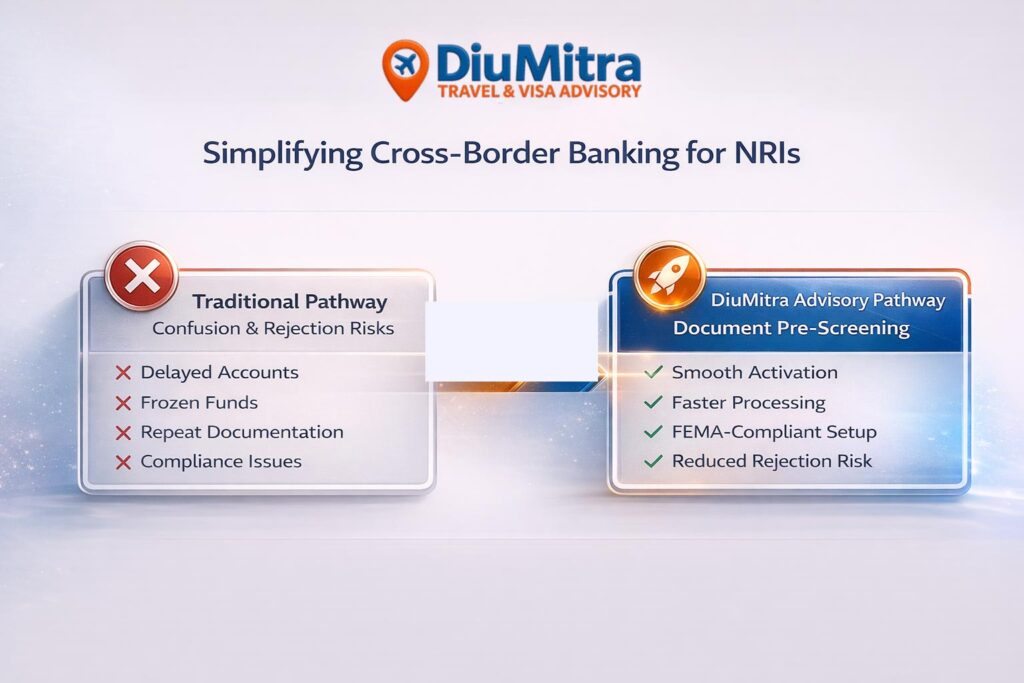
However, trying to open an NRE account from the UK or configure an NRO account for NRIs frequently turns into a major administrative headache. Indian financial institutions operate under strict regulations governed by the Reserve Bank of India (RBI) and the Foreign Exchange Management Act (FEMA). Because of stringent Anti-Money Laundering (AML) laws and strict international reporting guidelines under the Common Reporting Standard (CRS), a single minor error—such as a mismatched signature across decades-old forms, a poorly certified utility bill, or an incorrect selection on a multi-page application packet—can trigger instant rejections, frozen balances, or weeks of administrative loops.
At DiuMitra, we recognize the challenges of balancing your professional life in the United Kingdom with the strict paperwork expectations of offshore banks. You might be wondering: Do I need to queue at an Indian High Commission VFS centre just to certify my passport copy? How do I correctly manage tax liabilities under the UK-India Double Taxation Avoidance Agreement (DTAA)? Can I seamlessly transfer my rental collections out of an NRO account back to my UK bank account?
Our specialized UK India banking assistance program removes the anxiety from these scenarios. Acting as your administrative guide, we help you aggregate the correct dossiers, choose the appropriate account types for your goals, and audit your application forms page-by-page before submission. We take care of the structural heavy lifting so you can focus entirely on growing your cross-border wealth safely.
Comprehensive Overview of NRI Banking: NRE vs. NRO Accounts
Choosing the correct account configuration under FEMA guidelines is the single most critical decision of your cross-border strategy. Misunderstanding these account types can lead to accidental non-compliance or unintended tax liabilities with the Indian Income Tax Department.
Non-Resident External (NRE) Accounts
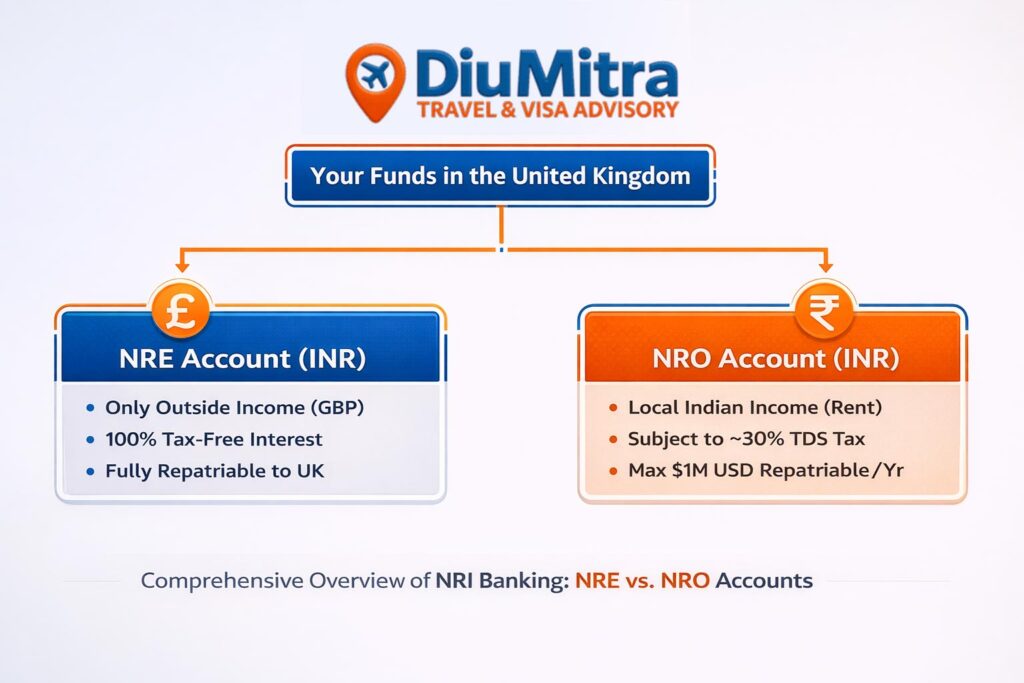
An NRE account is an interest-bearing account designed solely for placing external foreign currency savings converted cleanly into Indian Rupees (INR).
- Source of Legitimate Funds: You can only deposit foreign currency earned outside of India (such as Great British Pounds sterling). Local income generated inside India cannot be placed into an NRE portal.
- Tax Status In India: The interest accumulated on savings balances or non-resident fixed deposits is completely tax-free within India.
- Repatriation Pathways: Both your principal capital and accumulated interest are completely and freely repatriable. You can transfer funds directly back to your UK clearing bank without regulatory limits, caps, or specialized tax clearance forms.
Non-Resident Ordinary (NRO) Accounts
An NRO account acts as a designated repository for managing local, domestic income generated inside the borders of India.
- Source of Legitimate Funds: This format is perfect for depositing Indian earnings like rental revenue from properties in Ahmedabad or Anand, dividends from domestic equities, pensions, or local property liquidation values. You may also deposit foreign currencies into this account.
- Tax Status In India: Interest income earned inside an NRO account is taxable. It faces a base Tax Deducted at Source (TDS) rate of 30% plus surcharges. However, by implementing provisions of the UK-India Double Taxation Avoidance Agreement (DTAA), this rate can frequently be optimized or reduced down to 15% with appropriate tax documentation.
- Repatriation Pathways: Repatriation from an NRO asset is structurally restricted. Under standard RBI guidelines, you are allowed to transfer up to $1 million USD (or its equivalent value in GBP) per financial year out of India. This process requires a Chartered Accountant to verify tax clearances using Form 15CA and Form 15CB.
For a full regulatory breakdown of tax withholding rates and FEMA compliance rules, read our Detailed UK NRI Guide on NRE vs NRO Accounts.
Analytical Comparison Blueprint
| Financial Parameter | NRE Account | NRO Account Compare |
|---|---|---|
| Primary Purpose | Saving UK earnings and foreign income in Indian Rupees. | Managing income generated within India. |
| Deposit Sources | Foreign earnings only (GBP, USD, EUR and other overseas income). | Indian income such as rent, dividends, pensions, property sale proceeds and foreign remittances. |
| Tax Status | Interest income is generally tax-free in India for eligible NRIs. | Interest is taxable and subject to applicable TDS requirements. |
| Repatriation | Funds are freely repatriable and convertible to overseas accounts. | Subject to RBI and tax compliance requirements, with annual remittance limits. |
| Joint Holding | Usually held jointly with another NRI, PIO or OCI holder. | Can be held jointly with an NRI or eligible Resident Indian relative. |
| Investment Use | Suitable for investments where repatriation flexibility is important. | Commonly used for managing local property and domestic financial obligations. |
| Best Suited For | NRIs earning income predominantly outside India. | NRIs receiving regular income or maintaining financial commitments within India. |
Who This Service Is Specifically Designed For
Financial residency rules under FEMA operate independently from your legal passport citizenship. Our NRI Banking Support UK program provides tailored administrative pathways depending on your exact documentation background:
Indian Passport Holders Living in the UK (NRIs)
If you hold an Indian passport but reside in the United Kingdom on a Skilled Worker Visa, Health and Care Worker Visa, Spouse Visa, or a long-term Student Visa, your status shifts. Once you spend more than 182 days outside India during a single financial year, you are legally classified as an NRI. Under Indian law, you must transition your existing domestic savings accounts to NRO status to avoid heavy compliance penalties. If your primary identification records are expiring amidst this regulatory transition, ensure you secure your status by reading our comprehensive Indian Passport Renewal Support Guide.
British Citizens of Indian Origin (OCI Cardholders & PIOs)
If you have naturalized as a British citizen, surrendered your Indian passport, and hold a valid Overseas Citizen of India (OCI) card, you remain fully eligible to maintain an Indian rupee bank account UK. However, your documentation requires meticulous preparation to satisfy strict KYC audits regarding ancestral links, name changes, and legal nationality transitions. Need to verify your ancestral citizenship documentation before updating bank profiles? Read our step-by-step OCI Application Help Guide.
Families Managing Cross-Border Properties & Inheritances
If your family is based in areas with thriving British-Indian communities like Wembley, Southall, Leicester, or Coventry, and you suddenly inherit ancestral land, you cannot use a standard resident bank account to process the transactions. An NRO framework is the legally required mechanism to collect rent, clear local municipal property taxes, or collect asset sale funds transparently.
Corporate Professionals and UK Expatriates Relocating to India
If you are a British national moving temporarily to major commercial hubs like Mumbai, Bengaluru, or Delhi for a corporate assignment, building out a clean NRE/NRO link beforehand is vital for smooth international salary remittances and local expense management.
Comprehensive Documentation Checklist
Improper document formatting is the primary reason international bank applications are delayed or returned. Indian compliance offices require explicit validation steps to safeguard against identity theft, fulfill international Know Your Customer (KYC) frameworks, and maintain strict anti-money laundering compliance.
Depending on your citizenship path, you must prepare the following specific structural documents:
For Indian Passport Holders (NRIs):
- Valid Indian Passport: High-resolution, clear, and legible copies of the first page (photo page), last page (address page), and any pages containing legal observation remarks or valid entry stamps.
- Valid UK Visa / Residency Status: Official printouts of your digital UKVI share code proving your legal right to reside in the United Kingdom, your valid visa vignette, or your Biometric Residence Permit (BRP) card if still within its valid operational window.
- Proof of UK Residential Address: Official documents issued within the last 3 calendar months. Acceptable documents include utility bills (gas, electricity, or landline water bills), a current UK bank checking account statement, or a recent council tax bill. Note: UK driving licenses are explicitly rejected as proof of address by most major Indian financial compliance desks.
- Passport-Sized Photographs: Multiple recent color photographs displaying a clear, un-obscured face against a stark, plain white background.
- Financial Identity Identifiers (PAN Card): A legible copy of your Indian Permanent Account Number (PAN) card. Essential for seamless cross-border financial tracking and avoiding emergency-rate tax penalties on NRO portals, discover how to secure your tax identifiers via our PAN Card for NRIs Portal. If you do not legally possess a PAN card, a fully executed and signed Form 60 declaration is mandatory to accompany the application dossier.
For British Passport Holders (OCI Cardholders):
- Valid UK Passport: High-resolution color copies of the primary photo identification and data pages.
- Valid OCI Card / PIO Card: Clear copies of the front and back pages detailing your official overseas citizenship status.
- Proof of Indian Origin (If OCI is Pending): If you are in the process of applying and do not possess an OCI card yet, you must provide a copy of your surrendered Indian passport alongside an official Renunciation Certificate.
- Proof of UK Residential Address: Recent utility accounts, council tax papers, or bank statements matching your current United Kingdom residence exactly.
- Passport-Sized Photographs: Recent identical color photos with an un-obscured face against a solid white background.
- Financial Identity Identifiers (PAN Card): A valid Indian Permanent Account Number (PAN) card copy or a completed Form 60 declaration. This is highly critical for OCI holders to prevent financial institutions from applying maximum withholding taxes on local investment gains.
Navigating the Certified Attestation Hurdle
Because processing and underwriting units based in India cannot view your physical UK identity documents, all submitted photocopies must be legally verified and certified before your application is mailed. Our team provides clear operational guidance on completing these mandatory verifications through the only three legally acceptable channels:
- In-Branch Bank Verification: Authorized signature officials working inside international branches of registered Indian banks operating within the UK (e.g., State Bank of India UK, ICICI Bank UK, or Bank of Baroda UK).
- Legal Professionals: A registered Notary Public or certified legal solicitor practicing and registered within the United Kingdom.
- Consular Services: Consular officers at the High Commission of India or designated regional VFS Global centers under the official “Consular Miscellaneous” services window.
The Step-by-Step Process: How It Works
Navigating international bank applications can feel overwhelming. DiuMitra breaks your application journey down into five clear, manageable phases.
We look at your specific long-term goals. For example, if you tell us, “I am based in Edinburgh and need to manage rent from a commercial storefront in Pune,” we will guide you directly to an NRO account layout. If you intend to remit surplus sterling salary savings to take advantage of favorable Indian interest rates, we will prioritize an NRE fixed deposit pathway.
You provide us with digital copies of your passport files, address records, and residency paperwork. Our specialized review team examines them page-by-page. We look for hidden errors—such as subtle name spelling variances across old records, mismatched signatures, or outdated utility formats—so they can be corrected before submission to the bank’s compliance desk.
We help you navigate the multi-page application forms of your selected bank. We make sure critical global contact details, such as your UK mobile number (with the essential +44 country prefix) and primary email addresses, are placed in the correct boxes. This steps ensures your secure digital login credentials and OTP lines function properly on your UK phone.
We provide clear directions for completing your mandatory identity verification. Depending on your location and chosen bank, we will show you the most efficient validation path—whether that means setting up an appointment at a local UK branch office or using a secure remote digital KYC workflow.
Once your physical document bundle is sent to the bank’s international hub in India, we track its progress. We help you address any follow-up clarification requests from the bank’s underwriting teams until your accounts are opened, your welcome kits are generated, and your secure online portal goes live.
Common Pitfalls & How DiuMitra Protects You
Without structured guidance, cross-border bank applications often hit frustrating delays. Here are real-world challenges faced by applicants and how our service helps you avoid them:
Pitfall 1: Minor Name Discrepancies Across Legacy Documents
Real Scenario: A client living in Leicester holds a British passport issued under her married name (“Sarah Patel”), but her ancestral property titles and old Indian identity papers are listed under her maiden name (“Sarah Shah”).
The DiuMitra Fix: We catch these discrepancies early and help you organize the exact legal name affidavits or marriage verification links needed to satisfy the bank’s compliance team.
Pitfall 2: Failing to Convert Old Savings Accounts
Many Indian citizens move to the UK and leave their old domestic savings accounts active. This is a technical violation of FEMA rules and can result in account freezes or severe legal penalties. We help you systematically convert these old accounts into fully compliant NRO accounts without disrupting active standing orders or local direct debits.
Pitfall 3: Dropped OTPs and Inoperable Mobile Banking Apps
A major point of frustration for British-Indians is installing a banking app that fails to send verification One-Time Passwords (OTPs) to UK mobile networks. We verify that your forms explicitly request international profile routing, ensuring your security alerts and transfer codes arrive safely on your UK mobile phone.
Transparent Service Options & Processing Timelines
At DiuMitra, we maintain a clear, upfront fee structure. We operate on a flat-rate administrative support model, ensuring you know all fees before your document check begins.
Our Administrative Support Packages
| Feature | Premium Document Review Package | Comprehensive End-to-End Support Most Popular |
|---|---|---|
| Ideal For | Self-starters who need their application documents reviewed for accuracy before submission. | Busy professionals and families seeking a fully managed administrative support experience. |
| Document Review | Full digital review of identity and address documents. | Full digital review combined with comprehensive application support. |
| Error Checks | Pre-screening for typos, name discrepancies and signature issues. | Detailed verification with guidance throughout the preparation process. |
| Application Guidance | Detailed certification and document preparation guidance. | Dedicated form-completion assistance and cross-border consultation support. |
| Attestation Support | General certification guidance. | Clear attestation instructions tailored to your application requirements. |
| Additional Assistance | Self-managed after document review. | Direct bank liaison tracking and administrative follow-up support. |
| Communication | Guidance delivered during the review process. | Priority WhatsApp check-ins and ongoing support throughout the process. |
Please Note: Our service fees cover our dedicated administrative assistance, tracking support, and documentation review. Any separate banking fees, minimum initial deposit balances, notary public fees, or courier postage costs are paid directly to the respective third parties.
Expected Processing Windows
Serving the Indian Diaspora Across the Whole UK
No matter where you are located in the United Kingdom, DiuMitra provides comprehensive administrative support tailored to your regional processing requirements:
- Local Consular Advisory: We provide location-specific advice adjusted to the unique workflow preferences and operational rules of regional VFS submission facilities. Whether your appointment is scheduled in London (Goswell Road or Hounslow), Leicester, Birmingham, Manchester, Bradford, Cardiff, Edinburgh, Glasgow, or Belfast, our team ensures your packet meets the precise local expectations of that jurisdiction.
- Nationwide Remote Support: You never need to travel to an office to prepare your folder. We offer high-security document reviews via encrypted remote channels, accompanied by clear, friendly, and culturally supportive communication available in English, Gujarati, and Hindi. This allows you to finalize your complete paperwork safely from the comfort of your living room.
Frequently Asked Questions
Here are answers to the most common NRO Banking queries, simplified for UK residents:
Your Gateway to Secure Wealth Management
Setting up your financial foundations across the UK and India does not have to be a confusing or stressful chore. By selecting the correct NRE or NRO account setup, preparing clear document bundles, and following Reserve Bank of India rules closely, you protect your hard-earned savings and build a secure financial future for your family.
With DiuMitra as your administrative support, you gain a trusted partner who understands both your life in the United Kingdom and your administrative requirements in India. We clean up confusing jargon, eliminate paperwork errors, and provide a clear, step-by-step path to get your account activated successfully on the very first try.
Ready to set up your cross-border accounts without the typical stress? Connect with our advisory team today:
Typical response time: within 24 hours on weekdays.
⚠️ Comprehensive Advisory Disclaimer: DiuMitra is an independent, private administrative document support service and is not affiliated with the Reserve Bank of India (RBI), the Income Tax Department of India, HM Revenue & Customs (HMRC), or any commercial banking institution. We provide data compilation, document pre-screening, layout verification, and administrative advisory assistance to help clients avoid paperwork errors and application rejections. We do not operate as a licensed financial institution, chartered accounting firm, or legal practice, nor do we hold banking authority, issue account numbers, or guarantee tax approvals. All final decisions regarding account activation, NRE/NRO conversions, DTAA tax relief, and capital repatriation rest entirely with the underwriting officers of the respective banking institutions and regulatory authorities.
Contact Our Team
📞 +44-7424863463
📧 info@diumitra.com
🕒 Mon–Sat, 9 AM – 6 PM (UK)
Service area: Leicester, Wembley, London, and UK-wide journeys involving Leicester