Independent Money Transfer to India Advisory & Compliance Services
Avoid sudden transaction freezes, navigate complex HMRC and RBI compliance limits, and discover the most tax-efficient pathways for your family capital. DiuMitra provides independent, expert advisory services tailored specifically for the UK-Indian diaspora.
- Author Name: DiuMitra Cross-Border Advisory Team
- Reviewed By / Subject Matter Expert Name: Reviewed by Senior NRI Compliance & Banking Specialist
- Last Updated Date: Updated for 2026 Regulations (FEMA & HMRC DTAA Guidelines)
⚠️DiuMitra is an independent community consultation hub. We do not process financial transactions, handle physical remittance volumes, or act as an Financial Conduct Authority (FCA) regulated money transmitter. All support pathways are strictly advisory, curated to help the UK diaspora evaluate safe third-party remittance networks, structure their documentation correctly, and navigate international compliance frameworks smoothly.
UK-Based Travel & Visa Help
Step-by-Step Guidance
Trusted by British-Indian Families
Clear Fees — No Hidden Costs
Navigating Cross-Border Wealth Management & Compliance
Moving your hard-earned money across international borders is rarely as simple as clicking a button. For the British-Indian diaspora, initiating a money transfer to India involves balancing two entirely different financial legal systems. Whether you are sending regular maintenance funds to aging parents in Ahmedabad, liquidating a UK property asset to invest in real estate in Punjab, or managing ancestral wealth, the process can quickly become overwhelming.
Many families assume that choosing a remittance route is simply a matter of finding the lowest fee or the highest exchange rate. However, the reality of modern international banking is shaped by strict automated security systems, anti-money laundering (AML) protocols, and complex tax regulations. A sudden, unexplained transaction freeze can leave your funds stuck in limbo for weeks, causing immense anxiety and disrupting time-sensitive commitments.
At DiuMitra, we understand the unique pressures faced by Non-Resident Indians (NRIs), Persons of Indian Origin (PIOs), and UK expats. You are not just moving currency; you are moving life savings, family inheritances, and security.
Our specialized advisory service acts as a protective human shield between you and automated transactional systems. We do not handle your money. Instead, we audit your financial paperwork, clarify your regulatory obligations under both UK and Indian law, and guide you toward the safest, most efficient channels before you execute a transaction. We treat your family’s financial security with the absolute respect, precision, and clarity it deserves.
The DiuMitra Cross-Border Advisory Architecture
The DiuMitra compliance portal provides a dedicated, non-transactional environment to help you navigate international transfers safely. Our primary objective is to deliver complete visibility into cross-border financial operations, eliminating administrative blind spots before they trigger bank holds or compliance inquiries.
When you consult with a DiuMitra community advisor, we evaluate your upcoming transfer across three core dimensions:
- The Origin (UK Compliance): Verifying that your source of funds documentation complies with formatting guidelines required by UK clearing banks under the Money Laundering Regulations 2017.
- The Intermediary (The Route): Analyzing high-street banks and digital remittance platforms to identify hidden exchange rate markups and select the optimal channel for your transfer volume.
- The Destination (Indian Compliance): Structuring your transfer in accordance with Reserve Bank of India (RBI) inward remittance frameworks and the Indian Income Tax Act to protect recipients from unexpected tax liabilities.
Target Advisory Profiles & Client Portfolios
Our independent consulting framework is intentionally designed for individuals navigating high-value, complex, or sensitive financial transitions that standard automated customer support channels fail to address.
1. Cross-Border Estate Asset Liquidation & Wealth Transfer
If you live in Leicester and have recently sold a UK property to fund an ancestral estate project in India, or if you are managing the cross-border distribution of an estate, standard apps will often flag your transaction. We help you assemble clear, step-by-step documentation to satisfy both HMRC and Indian tax authorities.
2. Non-Resident Indian (NRI) Portfolio & Liquidity Optimization
Understanding transfer money from uk to nre account rules is critical to avoiding long-term tax complications. If you are a professional based in London or Birmingham trying to optimize your Indian savings balance, we guide you on how to split funds correctly between Non-Resident External (NRE) and Non-Resident Ordinary (NRO) accounts to preserve your right to repatriate capital later.
3. Generational Family Maintenance & Capital Support
For those sending regular, substantial living allowances to elderly relatives in regions like Gujarat, Punjab, or Kerala, we help you structure these transfers under authorized RBI purpose codes. This guarantees that your family members can access their funds immediately without receiving stressful compliance inquiries from local Indian banks.
Core Advisory Specializations
To comply with the UK’s Financial Conduct Authority (FCA) regulations and India’s Foreign Exchange Management Act (FEMA), service providers must verify your identity and, in some cases, the source of your funds. Being prepared with the correct documentation prevents unexpected processing delays.
Depending on your citizenship path, you must prepare the following specific structural documents:
HMRC Compliance & Source of Funds Verification
UK banks utilize advanced AI algorithms to scan outgoing international wires. Transactions that deviate from your normal banking patterns—particularly transfers exceeding £8,000—frequently encounter automated compliance holds.
DiuMitra helps you perform a pre-transaction documentation audit. We ensure your paperwork, such as HMRC P60 records, investment liquidation statements, or certified property contracts, is organized properly. This clear organization allows you to quickly satisfy any automated compliance challenges your bank may present.
NRI Banking Structuring (NRE vs. NRO Accounts)
Choosing the wrong destination account type in India can lead to unintended tax liabilities and compliance issues under the Foreign Exchange Management Act (FEMA).
- NRE Accounts: Hold foreign earnings, are completely tax-free in India, and allow you to freely transfer money back to the UK.
- NRO Accounts: Manage income earned within India (such as local rental revenue or pensions) and are subject to Indian income tax and strict annual repatriation limits.
We carefully review your financial goals to ensure your funds are routed to the correct account type, helping you avoid accidental tax penalties.
Choosing between repatriable and non-repatriable destination accounts requires careful evaluation. Review our deep-dive NRE vs NRO account tax rules guide to understand interest taxation and annual repatriation limits.
RBI Inward Remittance Frameworks & Purpose Code Assignment
The Reserve Bank of India closely monitors all foreign currency entering the country. Every transfer must be tagged with a specific, highly accurate “Purpose Code” that explains the nature of the transaction. Selecting an incorrect code can cause your Indian bank to withhold the funds or flag the deposit for an audit. We help you identify the correct code for your specific situation, keeping your transaction moving forward smoothly.
For a granular breakdown of exchange rates, transaction fees, and transfer speed comparisons across popular digital platforms, read our comprehensive UK to India money transfer guide.
Comparative Analysis: Institutional Banks, Digital Fintechs & Independent Advisory
To understand why independent advisory matters, it helps to look at how traditional transaction processors handle your money.
| Core Service Pillar | High-Street UK Banks | Automated Fintech Apps | DiuMitra Advisory Service |
|---|---|---|---|
| Operational Mandate | Processes wire transfers directly, often with high administrative overhead. | Automates digital transactions via mass software algorithms. |
✓ DiuMitra Advantage Provides independent, human-led compliance guidance and strategy. |
| Exchange Rate Visibility | Often adds hidden currency markups ranging from 3% to 5% above the mid-market rate. | Offers variable, app-dependent rates that fluctuate throughout the day. |
✓ DiuMitra Advantage Unbiased, independent analysis to help identify the most cost-effective provider. |
| HMRC / RBI Legal Support | None provided to retail or NRI banking clients. | Automated system flags with no live compliance advisory. |
✓ DiuMitra Advantage Hands-on assistance to help organise purpose codes and verify source-of-funds requirements. |
| NRE / NRO Setup Direction | Limited cross-border insight into Indian banking structures. | No structural support for specialised NRI accounts. |
✓ DiuMitra Advantage Comprehensive guidance for managing your cross-border NRI finances. |
| Support Environment | Long phone queues and rigid institutional processes. | AI chatbots and ticketing systems. |
✓ DiuMitra Advantage Direct, personalised support deeply connected to the community. |
UK & Indian Financial Compliance Frameworks
UK Regulatory Landscape: Anti-Money Laundering (AML) & Source Verification
Under the Money Laundering Regulations 2017, UK financial institutions face strict legal penalties if they do not verify the origin of large outward international transfers. This scrutiny often intensifies for destinations outside the UK and Europe.
Real-World Scenario: Imagine you are a resident living in Southall who wants to send £15,000 to India to pay for a relative’s urgent medical procedures. If you simply transfer the funds from your standard checking account without preparing the underlying bank documentation, your bank’s automated compliance system may place an immediate freeze on your account.
DiuMitra helps you organize your certified savings statements and proof of earnings before you make the transfer, helping you avoid stressful, sudden account freezes.
Indian Tax Compliance: Income Tax Act Section 56(2)(x) Regulations
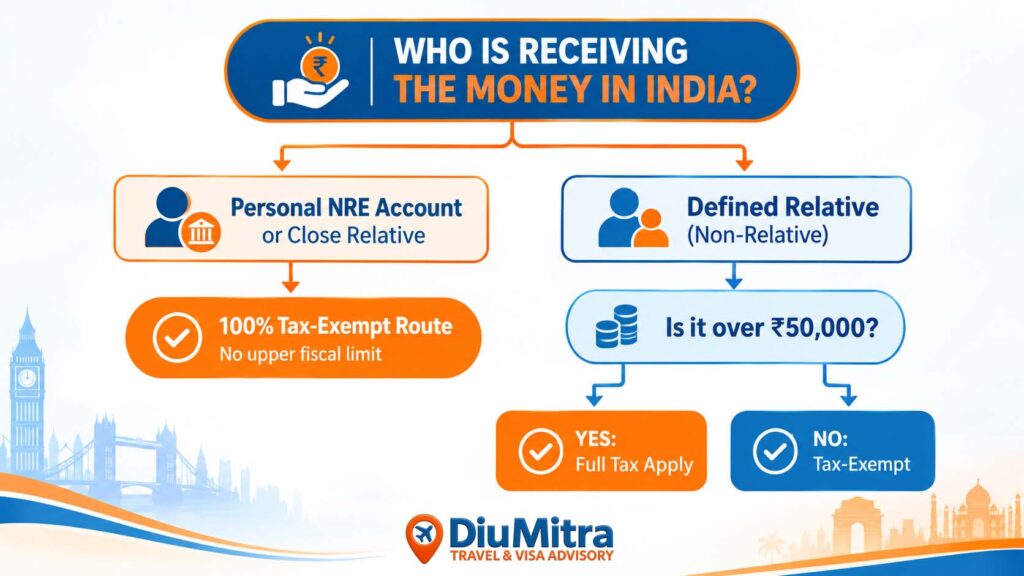
A common question we receive from the community is: how much money can I send to India from UK without tax? The answer depends entirely on who is receiving the funds.
Under Section 56(2)(x) of the Indian Income Tax Act, remittances sent to individuals defined as “close relatives” carry absolute tax immunity. The Indian government defines close relatives as:
- Your spouse
- Your parents and grandparents
- Your siblings (brothers and sisters)
- Your direct lineal descendants (children and grandchildren)
However, if you send money to a non-relative (such as a business partner, a distant cousin, or a friend), any amount exceeding ₹50,000 (approximately £500 to £600 depending on current exchange rates) within a single fiscal year triggers full income tax liabilities for the recipient in India. Senders transferring capital directly to their personal NRE accounts experience zero tax exposure.
RBI Inward Remittance Channels: RDA vs. MTSS Frameworks
The Reserve Bank of India regulates money entering the country through two distinct frameworks, depending on the speed and purpose of the transfer:
- The Rupee Drawing Arrangement (RDA): This is the preferred channel for major cross-border banking deposits and long-term investments. The RDA allows you to route money directly into native NRE accounts with no fixed upper financial cap. However, it cannot be used for physical cash payouts within India.
- The Money Transfer Service Scheme (MTSS): This channel is designed strictly for swift family maintenance and personal support. Under rbi inward remittance rules 2026, MTSS transfers are capped at a maximum of $2,500 USD equivalent per transaction, and a single beneficiary can receive a maximum of 30 transfers within a single calendar year. Physical cash payouts are permitted through authorized agents, but these funds cannot be deposited directly into an NRE account.
Pre-Transaction Compliance Verification Checklist
Before you initiate a major international transfer, our advisors help you gather and review a clear set of documents based on your specific situation. This preparation ensures that if a bank or compliance algorithm requests verification, you can respond instantly with accurate, well-organized paperwork.
Documentation for UK Source of Funds Verification
- Employment Income: 3 to 6 months of official UK bank statements showing your salary deposits, alongside your most recent HMRC P60 document or formal payslips.
- Property Dispositions: A certified copy of the final completion statement from your UK solicitor, alongside proof of the property registration transfer.
- Investment Liquidation: Official closing certificates or stock liquidation summaries showing the payout from a UK-regulated brokerage firm or investment fund.
Beneficiary Verification & Relationship Documentation
- Relationship Verification: Valid passport copies, birth certificates, or family OCI documentation that clearly establishes the family connection between the sender and the recipient under Section 56(2)(x).
- NRI Account Credentials: Formal bank-issued confirmation showing the exact status of the destination account (clearly distinguishing between NRE and NRO status).
- Purpose Code Assignment Form: A pre-filled documentation layout mapping the exact RBI purpose code (e.g., P0011 – Personal transfers or P0014 – Family maintenance) to prevent processing delays at the receiving bank branch.
The Advisory Workflow: From Consultation to Execution
Navigating your cross-border transfer with DiuMitra is designed to be simple, supportive, and clear. Here is how we work together:
We start with a friendly, comprehensive consultation—either via WhatsApp or a secure scheduled call—to review your transfer goals. We discuss the estimated amount you want to transfer, who will receive it, and your long-term financial plans.
Your dedicated advisor reviews your financial paperwork to identify any potential compliance flags under HMRC or RBI guidelines. We ensure your source of funds documents are well-organized and match the required formats, and we help you select the exact RBI purpose codes for your transaction.
We provide an unbiased analysis of the current remittance market. We show you the actual costs, processing speeds, and hidden exchange rate markups of different transfer routes, helping you choose the most secure and cost-effective option for your specific transaction size.
With your documentation organized and your route selected, you can initiate the transfer directly through your chosen provider with confidence. Your DiuMitra advisor remains available to provide clear guidance if your bank asks any unexpected compliance questions.
Remediation Pathways for Common Compliance Disruptions
Even carefully planned transfers can occasionally hit automated delays. Here is how our team helps you handle common challenges:
Outgoing Transaction Freezes by UK Financial Institutions
- The Problem: Your UK bank abruptly stops an outgoing international wire, flags the transfer as “high risk,” or requires you to prove the origin of the funds within a short timeframe.
- How We Help: We help you quickly organize your pre-audited financial documents into a clear package that satisfies the bank’s compliance team, helping to resolve the hold as quickly as possible.
Beneficiary Bank Compliance Holds in India
- The Problem: The money leaves the UK successfully but is held by the intermediary or receiving bank in India due to an missing or mismatched purpose code.
- How We Help: We provide clear guidance on how to complete the bank’s verification forms, update the purpose code correctly, and establish the family relationship to release the funds smoothly.
Regulatory Non-Compliance Under FEMA & Account Misclassification
- The Problem: An NRI accidentally deposits local Indian income (like rental revenue or asset sales) directly into an NRE account, creating unintended tax liabilities under FEMA regulations.
- How We Help: We review your accounts to help you separate your funds correctly, routing local Indian income into NRO accounts and foreign earnings into NRE accounts to keep your finances fully compliant.
Advisory Service Tiers & Engagement Models
We believe in complete transparency, which is why our advisory fees are straightforward and completely separate from any transactions. Because we do not handle or process your funds, we never charge hidden commissions, percentage-based deductions, or added currency markups.
Standard Remittance & Compliance Verification
- Best For: Individuals sending one-off family maintenance or living support payments up to £10,000.
- What’s Included: Direct advisory support via WhatsApp, verification of the recipient’s tax-exempt status under Section 56(2)(x), and guidance on selecting the correct RBI purpose code.
- Fee Structure: Fixed, affordable consulting fee with zero hidden costs.
High-Value Capital & Estate Portfolio Consultation
- Best For: High-value transfers, property sales, asset liquidations, or managing complex family inheritances.
- What’s Included: A full, detailed review of your UK source of funds documentation, advanced guidance on routing wealth into NRE and NRO accounts, and hands-on support to prepare for potential HMRC and RBI compliance checks.
- Fee Structure: Fixed project-based consulting fee discussed transparently upfront.
Frequently Asked Questions
Here are answers to the most common money transfer to India queries, simplified for UK residents:
Initiate Your Cross-Border Transfer Compliance Review
Moving your family’s financial assets across borders should be a moment of milestone achievement, not a source of stress and regulatory worry. By preparing your documentation, understanding compliance thresholds, and setting up your destination accounts correctly, you can protect your hard-earned wealth from unexpected transaction holds.
At DiuMitra, we are here to support the British-Indian diaspora with clear, practical guidance. We help you navigate complex financial rules with confidence, ensuring your family’s future stays on solid ground.
Join the DiuMitra Diaspora Network
Avoid automated transaction delays and unexpected compliance questions. Get in touch with a DiuMitra community advisor today to review your paperwork and plan your transfer with confidence.
Typical response time: within 24 hours on weekdays.
Contact Our Team
📞 +44-7424863463
📧 info@diumitra.com
🕒 Mon–Sat, 9 AM – 6 PM (UK)
Service area: Leicester, Wembley, London, and UK-wide journeys involving Leicester